The AspenClosed August 2026

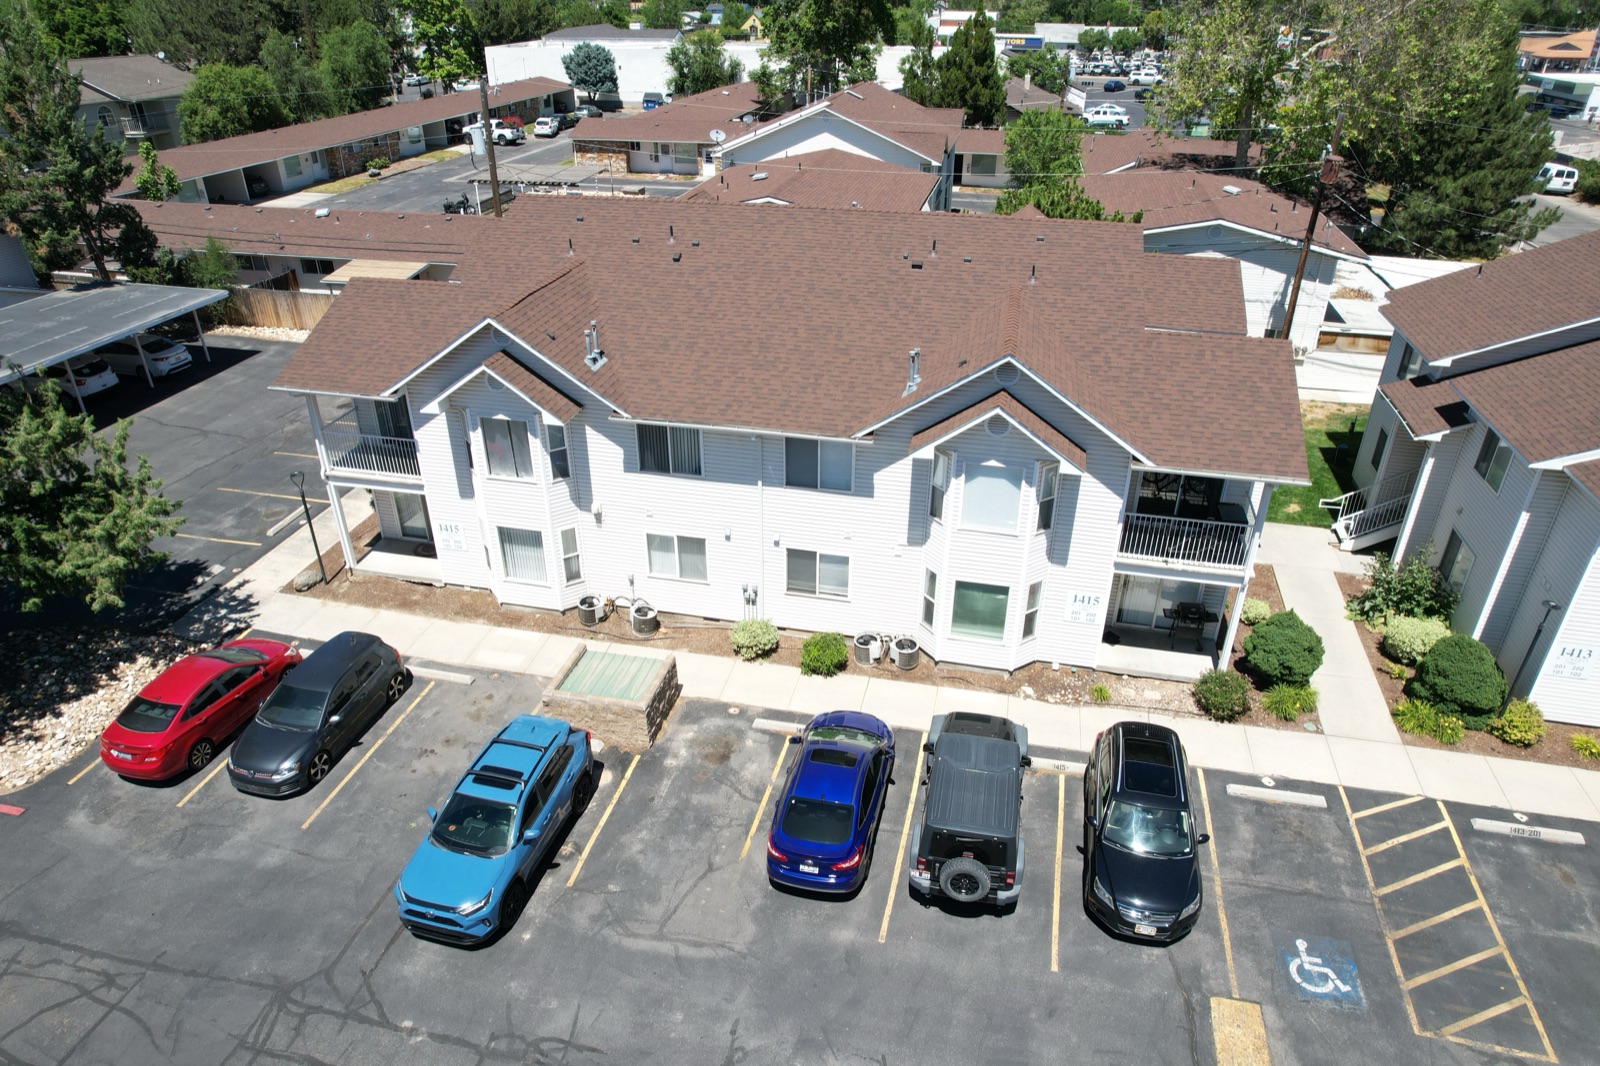
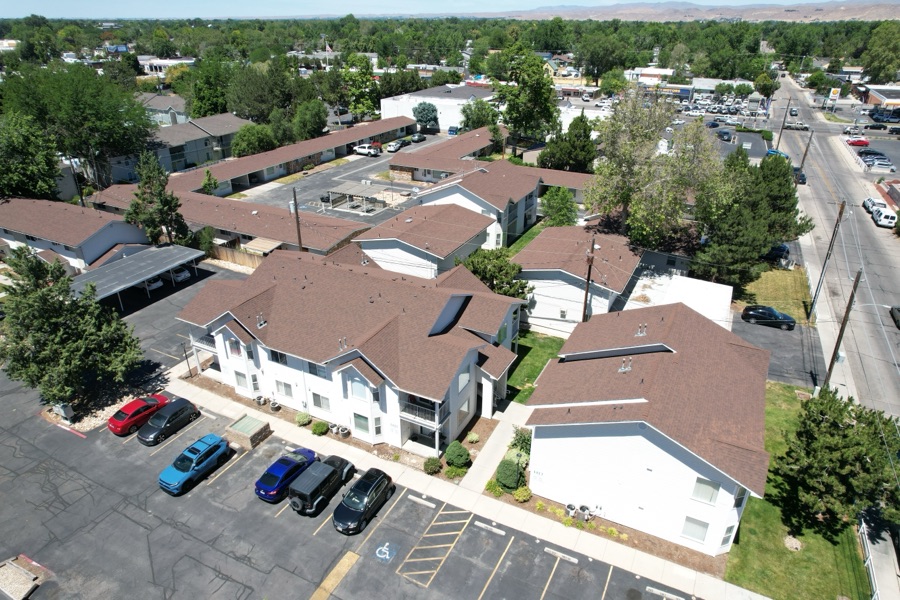
45 units across 12 buildings at 1411 to 1425 N Liberty Street, Boise. Workforce housing bought 100% occupied, with in-place rents below market.

The Aspen
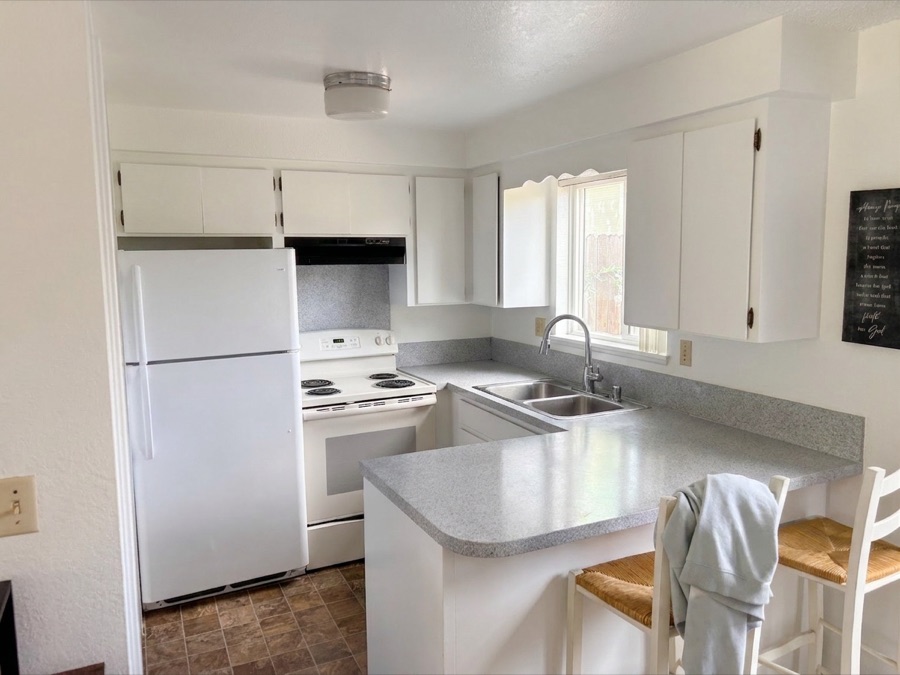
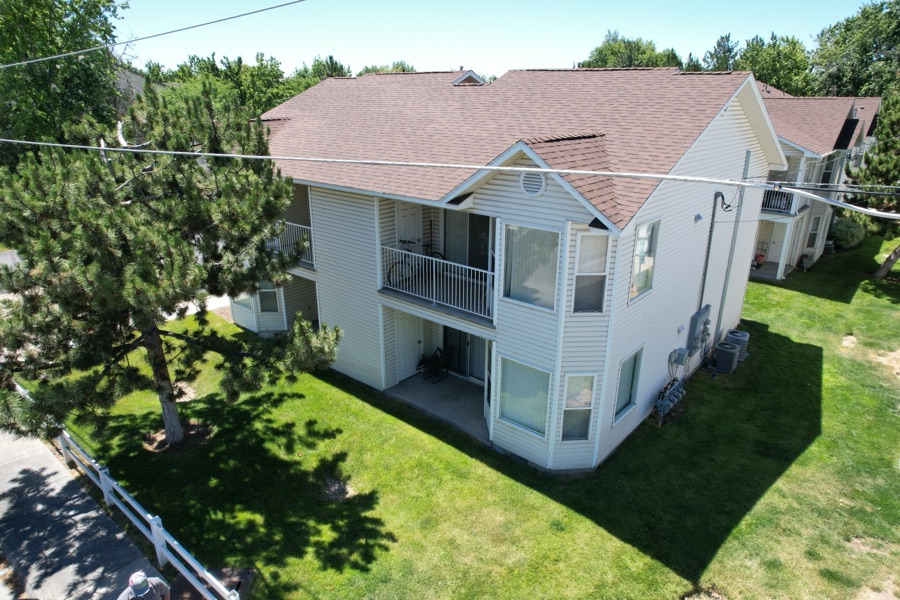
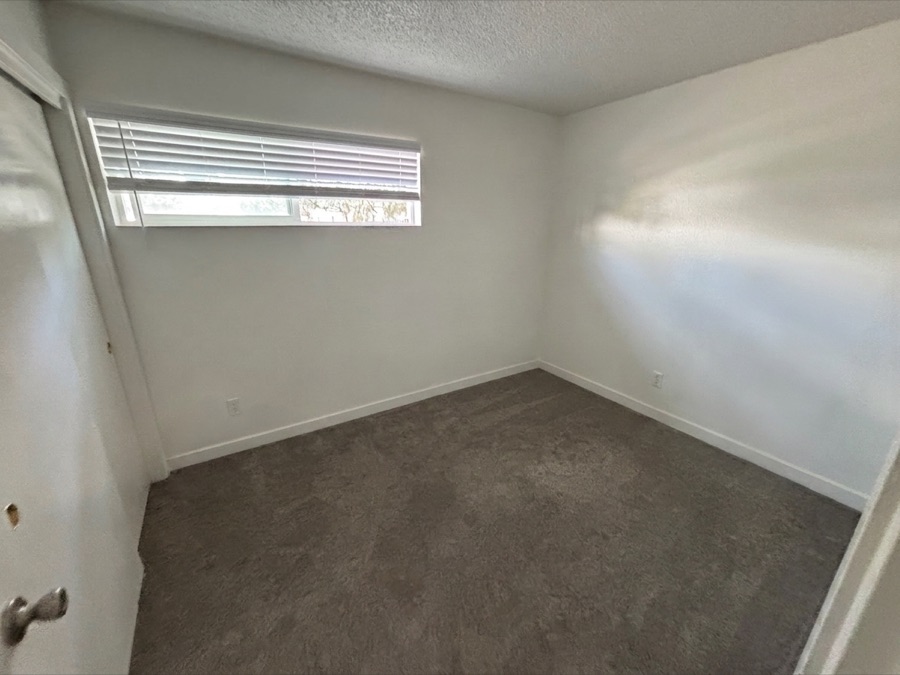
Building front Renovated kitchen Lawn and mature trees The complex from the street Bedroom
01

Key metrics

20.2%
targeted IRR, net to LPs
2.36x
targeted equity multiple, net to LPs
7.5%
targeted avg annual cash-on-cash
8%
preferred return to investors
70/30
split above the pref, in investors' favor
5 yrs
targeted hold
From the locked underwriting model, August 26, 2026 cut. Targeted, not guaranteed. A projection is the least reliable number on this page; the fees below are the most reliable. The downside case (flat rents, higher vacancy, higher expenses) is in the deal materials, and I'll run any scenario you want on a call.

What that looks like on your money

The same locked model, scaled to whatever you'd place. The monthly figure climbs because renovated units reach market rent on natural turns.

$100,000
$50,000 minimum $1,000,000
Projected 2026 depreciation allocated to you
$69,050 to $76,348

A first-year paper loss reported on your Schedule K-1, not cash. Base case to upside case. The cost segregation study is in progress, so this is a projection, and what it does on your return is your CPA's call.

Projected monthly distribution, by year

Paid monthly, starting November 1, 2026. It climbs because renovated units reach market rent on natural turns, not because rents are assumed to spike. The five-year average of these is the 7.5% cash-on-cash quoted above.

Projected total over a five-year hold
Cash distributions, years 1 to 5 $37,570
Return of your capital at sale $100,000
Your share of the profit at sale $97,983
Projected total back to you $235,553

Which is the 2.36x equity multiple and the 20.2% IRR on this page, net to you, after every fee and after my share of the profit. The sale is the least certain line here: it rests on an exit assumption five years out, and a building is worth what someone pays for it on the day.

Every figure here is a projection from the locked underwriting model, August 26, 2026 cut, scaled to the amount you chose. Distributions are pro rata to capital, so the arithmetic is exact, but the underlying projections rest on assumptions that may not prove correct and none of it is guaranteed. The depreciation range comes from two engineering proposals, not a delivered cost segregation study. This is not tax advice and it is not an offer; any offering is made only through the Fund's documents to verified accredited investors.

02

Offering summary

Purchase price$8,750,000
Price per unit$194,444
Units45, across 12 buildings
Rentable square feet37,844
Vintage1964 to 2000, core 1970
Cap rate at purchase5.63% on the seller's trailing twelve, as their books reported it
Financing$6,535,000 fixed-rate, non-recourse, interest-only for the full term
Occupancy at closing100%
ClosedAugust 28, 2026
03

Deal walkthrough

The investor webinar, recorded live on August 5, 2026, three weeks before closing. Some figures predate the final rate lock; the locked numbers are on this page.
04

The plan

Prior ownership turned eleven units during its hold, and the renovated units rent for about 24% more. The plan is the same play, on our timeline: renovate on natural turns, never trading occupancy for rate, with the renovation budget funded at closing rather than out of operating cash.

The property manager signed a written business plan before takeover: the budget, the renovation program, preventive maintenance schedules, the lender's operating requirements, and the service levels each side commits to. When something is ambiguous mid-year, the document is the tiebreaker.

05

The market underneath it

Two credible sources disagree about Boise rent growth, by a lot. You should see both, and you should know which one I underwrote to.

SourceWhat it measuresBoiseNational
Zumper, Sept 2026Asking rent, two-bedroom+15.9%+0.5%
Zumper, Sept 2026Asking rent, one-bedroom+11.5%+0.1%
Cushman & Wakefield, Q2 2026Same-store effective rent+3.1%+0.5%
Zumper National Rent Report, report dated September 28, 2026, year over year. Cushman & Wakefield Boise MarketBeat Multifamily, Q2 2026. The national figure on the third row is CBRE's Q2 2026 US number, a different publisher.

Both are right, and they count different things. Zumper measures what landlords are asking on units listed today, including houses and condos. Cushman measures what stabilized apartment portfolios actually collected across every lease, most of which were signed last year and have not moved yet. Asking rents turn first. In-place rents follow slowly. The spread between the two is roughly the opportunity this deal buys.

I underwrote to the slow number. The model carries 3.5% organic rent growth for the whole five-year hold, which sits just above Cushman's 3.1% and nowhere near the asking-rent figure. Everything beyond that comes from renovating units on natural turns and closing the gap on leases already below market, not from betting the market reprices. So if Boise does reprice the way those asking rents suggest, it is upside this plan does not need. And if you pull the Cushman report and find 3.1%, you should have known why before you saw it rather than after.

Where this building actually landed: the three renewals signed so far came in between 9.7% and 12.8%, nearer the asking-rent number than the institutional one. That is three leases and not a trend, and it is capture on rents that were below market to begin with rather than pure market growth. The monthly updates below are where that either continues or it does not.

06

Fees, stated first

If a fee only looks reasonable after you've seen the upside, it isn't reasonable. Here's what I earn on this deal.

FeeBasisOn The Aspen
Acquisition fee2% of purchase price, at closing$175,000
Guarantor feeFor signing on the loan$31,725
Asset management fee2% of collected income, ongoing2% of collections
Disposition fee1% at sale1% of sale price
The part that almost went wrong

Partway through escrow, my financing fell apart.

My earnest money was hard, the seller had a date, and the original lender was coming apart underneath the deal. So I took the debt back out to the market, worked it lender by lender, bought an extension, and closed on a fixed-rate, non-recourse loan with better terms than the one that died. I tell that story on purpose: you learn more about a sponsor from the week the financing broke than from any deck.

"Brent is a problem solver. When hurdles get in his way he finds a way through them. He's resourceful, honest, and follows through on his commitments. His approach to acquisitions is creative and strategic. The way he leverages technology to operate his portfolio sets him apart."
Chriskott Todd, Director of Investment Sales, Berkadia Real Estate Advisors. The listing broker on The Aspen.
07

Property updates

What actually happened at the property, month by month. The same update investors get, minus their individual numbers.

October 7, 2026

The first renewals are in, signed at the rents we underwrote

We closed The Aspen on August 28, so this is the first look at it under our ownership. The first renewals are in, leasing is marginally ahead of what we underwrote, and the fall turn schedule is where the work is.

43 of 45
units leased · 95.56% · Oct 7
$1,424
in-place average rent · Sept 22
$65,590
scheduled monthly rent · Sept 22

Leased and occupied are two different measures, so here are both. As of October 7 the building is 95.56% leased, 43 of 45 units, against the 95% we underwrote. It is 93.33% occupied, 42 of 45, because one of those signed leases has not moved in yet and two units are being turned. One more signed lease puts it near 97.8%.

Three units renewed at exactly the rents we underwrote. All three are one-bedrooms, each signed at the market rent its floor plan carries in the model: $1,525 on the two renovated, $1,325 on the classic. That is $450 a month, $5,400 a year, on three signatures and no renovation spend.

Three other residents gave notice instead of renewing. That is the outcome we want on the units furthest below market, because a turn moves rent further than a renewal can. Four residents sit on month-to-month.

The one-bedrooms: what we captured, what is left rent at takeover 1x1 Renovated 11 units $1,525 +$165 $1,360 +$135 $1,390 $250 to go $1,275 $230 to go $1,295 $230 to go $1,295 $225 to go $1,300 $125 to go $1,400 $125 to go $1,400 $100 to go $1,425 $95 to go $1,430 $75 to go $1,450 1x1 Classic 5 units $1,325 +$150 $1,175 $225 to go $1,100 $205 to go $1,120 $125 to go $1,200 above plan $1,350 total $450/mo captured $2,010/mo still in the thirteen leases that have not come up already above plan

All three renewals were one-bedrooms, so here are both one-bedroom plans, sixteen units. Each row starts at the rent that lease paid the day we took over. Navy is what we moved it. Pale is what is still sitting there. Each plan has its own underwritten rent, which is why there are two lines.

Across these sixteen units the building was collecting $2,460 a month less than the underwriting says they are worth. The three renewals took $450 of that, with no renovation dollars spent. The remaining $2,010 a month, $24,120 a year, sits in thirteen leases and does not move until they expire. One classic unit is already renting above its plan.

That is a value-add deal in month one: a small win and a long runway, and the only thing that turns one into the other is time and turns.

When we get to move rent 0 2 4 6 7 leases Oct Nov Dec Jan Feb Mar Apr May Jun Jul Aug Sep lease expirations, Oct 2026 through Sep 2027

Thirty-eight of the forty-five leases come up in the next twelve months. A lease expiring is the only moment the rent on that unit can change, so that schedule is the business plan. June is the heaviest at seven, and a cluster like that is an opportunity if the units are ready and a problem if they are not.

What's next. Three units turn before the end of October, the first we control start to finish. What they sign at will tell us more about the renovation plan than anything else this year. The lender's repair items are scheduled for completion this fall, on the loan's timeline.

Rent and loss-to-lease figures sourced from our property manager, September 22, 2026. Leased and occupied figures updated October 7, 2026. Underwritten rents from our locked underwriting model.

08

Documents

The full presentation, from the locked v4.5 model. Open to anyone, no email required
Aug 26, 2026
The deal in slides, same locked numbers
Aug 31, 2026
Private placement memorandum
Full terms, fees, and risk factors
Operating agreement
The entity investors own
Subscription agreement
Signed at investment, after accreditation verification

Investors in this deal receive a monthly report, monthly distribution, and monthly update, with the property manager's full report alongside mine.

09

Soft commit

A soft commit holds your place in line for the sponsor-held position. It's not binding and it doesn't move money; it tells me who's serious so I can reach out with the offering documents, usually the same day.

Your place is held in the order soft commits come in. Not an obligation, and accreditation is verified by a third party before any investment.